
Many people in their twenties and early thirties expected that a first real paycheck would bring financial breathing room. Instead, a growing number of young professionals report the same frustrating situation: their income is higher than their parents’ was at the same age, yet their bank balances stay thin and savings goals keep slipping further away. Financial commentators have a name for this, the “high income, broke” phenomenon, and it is becoming a common topic in personal finance conversations.
The problem is not simply that young workers are careless with money. Several structural forces, along with everyday spending habits, are working against them at the same time.
The Trap of Lifestyle Creep
The most familiar explanation is what personal finance writers call “lifestyle creep.” It happens gradually. A raise arrives, and a slightly better apartment seems affordable. A new job calls for a more polished wardrobe, a commute by ride-hailing app, and a regular coffee routine that feels like a small reward. Subscriptions for streaming, fitness, and meal kits pile up, each one cheap on its own.
None of these choices is irrational in isolation. The issue is that expenses tend to rise to match income. Behavioral economists describe a related idea called hedonic adaptation: people quickly get used to a better standard of living, so what once felt like a luxury soon feels like a baseline need. When the next raise comes, the new normal has already shifted upward, and the extra money disappears without much notice.
For young adults who grew up watching parents stretch every dollar, the temptation to finally enjoy the rewards of working hard is strong. Social media makes that temptation sharper, since feeds are full of travel, dining, and home décor that appear effortless. Comparison with peers can quietly shape what feels like “normal” spending.
Housing Costs Are Eating Up More of the Paycheck
Even careful budgeters face a steep challenge in housing. In many cities across the United States, Europe, and Asia, rents have risen faster than wages over the past decade. Young workers who move to large urban centers for better-paying jobs often find that the savings in salary are swallowed by rent, transport, and utilities.
Housing affordability is especially tough for people trying to build independence. Security deposits, moving costs, and furniture purchases can add up to thousands before the first full month of rent is paid. Many young adults also live alone or with a single roommate in expensive areas because they want privacy or a better work-life balance, and that choice carries a real price tag.
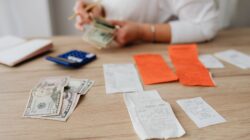
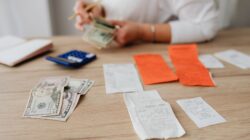
The result is a budget with less flexibility than the headline salary suggests. A person earning a comfortable figure on paper may still have little left after rent, debt payments, and basic living costs.
Debt That Follows Them Into Their Careers
Debt is another major factor. Student loans remain a heavy burden for millions of graduates, and repayment restarted in many countries after pandemic-era pauses ended. Monthly loan payments can take a significant share of take-home pay, leaving less room for emergency savings or investing.
Credit card debt adds another layer of pressure. Average credit card interest rates in the United States have hovered above 20 percent in recent years, according to Federal Reserve data, which means balances can grow quickly if only minimum payments are made. Buy now, pay later services have also spread rapidly, offering the chance to split purchases into small installments. These tools can feel painless at checkout, but they make it easy to commit future income before it has been earned.
Once debt payments become routine, they start to feel like fixed costs rather than choices. That mindset can make it hard to imagine a future where income is genuinely free to save or invest.
Few Savings and Little Financial Cushion
Surveys from the U.S. Federal Reserve’s Survey of Household Economics and Decisionmaking have repeatedly found that a large share of adults would struggle to cover an unexpected $400 expense using cash or its equivalent. Younger adults often appear among those most exposed. A car repair, a medical bill, or a sudden job gap can quickly push someone toward high-interest borrowing.
This lack of cushion explains why high earners can still feel financially fragile. Income may be strong, but without savings, a single surprise can erase months of progress. Many young professionals also delay building an emergency fund because they assume they will start “next year, when things settle down,” and the moment rarely arrives on its own.
Why Good Income Does Not Automatically Build Wealth
Earning more is only part of building financial security. Wealth depends on the gap between what comes in and what goes out, and on how consistently surplus money is saved and invested. A higher salary can widen that gap, but only if spending is kept in check.
Young adults may also lack financial education. Many schools teach little about budgeting, taxes, retirement accounts, or compound interest. People learn money habits from family, friends, and online content of varying quality. Without clear guidance, it is easy to make expensive decisions, such as carrying a balance on a credit card or leaving retirement contributions untouched because they seem distant.
There is also a timing issue. Retirement feels abstract at twenty-five, so saving for it competes with immediate desires like travel, dining out, or a better car. Starting early is one of the most powerful advantages in investing, yet it is often the one most easily postponed.
Practical Steps to Break the Cycle
The good news is that the high income, broke pattern can be reversed with deliberate choices. Experts commonly suggest a few practical habits:
- Automate savings so money moves to a separate account on payday before it can be spent.
- Review recurring subscriptions every few months and cancel those that no longer add value.
- Build an emergency fund gradually, aiming for several months of essential expenses.
- Set a rule for raises, such as directing a portion of every pay increase toward savings or debt repayment before adjusting lifestyle.
- Avoid unnecessary debt, especially high-interest credit card balances, and pay more than the minimum when possible.
- Start investing early, even with small amounts, to benefit from long-term compounding, particularly through workplace retirement plans that offer employer matching.
These steps are not glamorous, and they require discipline. But they shift the focus from earning more to keeping more, which is the foundation of lasting financial stability.
A Shift in Mindset
Ultimately, the struggle many young professionals face is less about a lack of income and more about the way money is managed in a fast-changing economy. Rising living costs, easy access to credit, constant social comparison, and limited financial education all play a role. Recognizing these pressures is the first step toward taking control.
A high salary is an opportunity, not a guarantee of security. Young adults who treat their first strong paychecks as a chance to build savings, reduce debt, and invest for the future are far more likely to convert earning power into real financial freedom. The goal is not to live frugally forever, but to make intentional choices so that income translates into progress rather than disappearing month after month.